
In this guide
Compound growth means later returns are calculated on the starting principal plus returns already added. Regular contributions can become just as important as the initial deposit, especially over long periods.
Investor.gov’s compound-interest calculator asks for initial investment, monthly contribution, time, estimated annual rate, a rate-variance range, and compounding frequency. Those inputs are a useful checklist for any projection.
Investor.gov, U.S. Securities and Exchange CommissionSeparate money added from growth earned
A final balance contains at least two components: money you contributed and growth on the balance. Report both. Otherwise, a large ending number can make it difficult to see how much came from saving behavior versus the assumed return.
For example, monthly contributions enter at different times. The first contribution may compound for years; the last has almost no time to grow. A calculator handles that schedule more accurately than multiplying one monthly contribution by a single growth factor.
Treat the rate as a scenario
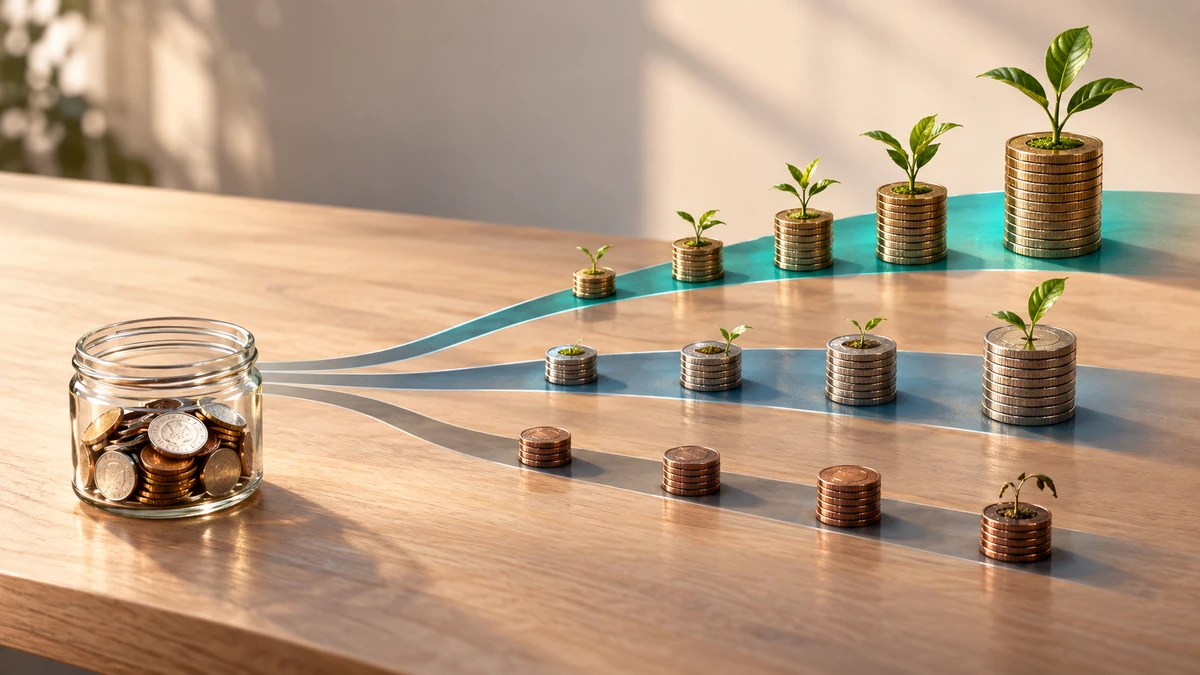
An estimated return is not a promise. Investor.gov includes a variance range so users can compare outcomes above and below the central estimate. That is better decision support than displaying only one precise-looking number.
Investor.gov, U.S. Securities and Exchange CommissionRun conservative, central, and optimistic scenarios. Keep contribution timing and time horizon constant so the effect of the assumed rate remains visible. For investment decisions, account fees, taxes, inflation, and volatility separately if the calculator does not include them.
- Initial principal sets the starting base.
- Regular contributions add new principal over time.
- Rate and time interact; small assumption changes can widen over long horizons.
Compounding frequency is not contribution frequency
Monthly compounding describes how often growth is credited under the model. Monthly contribution describes how often new money is added. They can be the same, but they are conceptually different inputs.
Use the calculator as a planning model, save the assumptions with the result, and revisit them when the contribution, horizon, or realistic rate changes.
Key takeaways
- Show contributions and estimated growth separately.
- Compare a range of rates instead of trusting one projection.
- Record the assumptions that produced the result.
Sources
References for factual claims and further reading.
- 01
Investor.gov, U.S. Securities and Exchange Commission
Compound Interest Calculator
Educational information only. Follow the requirements of the receiving organization, product label, applicable standard, or qualified professional for your situation.